Financial literacy is an important life skill that every young learner should develop. Money plays a major role in everyday life, and understanding how to manage it can help students make better decisions as they grow older. From buying school supplies to saving for future education, financial knowledge influences many personal choices. When children learn the value of money at an early age, they become more responsible, confident, and prepared for future financial challenges.
Financial education is not only about earning money or becoming wealthy. It teaches young people how to spend wisely, save regularly, understand financial responsibilities, and plan for future needs. These lessons are useful for students regardless of their family background or financial situation.
Schools and parents both have important roles in developing financial awareness among children. By introducing simple money management concepts through practical activities, young learners can build habits that support financial stability throughout their lives.
What Is Financial Literacy for Young Learners?
Financial literacy refers to the knowledge and skills needed to understand and manage money effectively. For young learners, it begins with simple concepts such as recognizing money, understanding prices, comparing costs, and learning the difference between needs and wants.
As students grow older, they can explore more advanced topics, including budgeting, saving, banking, responsible borrowing, and financial planning.
For example, a primary school student may learn to save a small amount of pocket money each week. A secondary school student may learn how to prepare a monthly budget or compare the prices of different products before purchasing them.
These activities help students understand that money is a limited resource and that every financial decision involves choices.
Financial literacy education provides practical knowledge that students can apply outside the classroom. It connects academic learning with real situations, making education more meaningful and useful.
1. Financial Literacy Teaches the Value of Money
One of the main reasons financial literacy is important for young learners is that it helps them understand the value of money.
Young children often see adults purchasing food, clothing, toys, and other products without fully understanding how money is earned. Financial education introduces the relationship between work, income, and spending.
Students learn that earning money generally requires time, effort, skills, or resources. They also understand that families must make financial decisions based on available income.
For example, when a child receives pocket money, parents can explain how that amount can be used for different purposes. The child may choose to purchase a small item immediately or save the money for something more valuable.
Such experiences encourage children to appreciate financial resources and avoid unnecessary spending.
Understanding the value of money also promotes respect for the efforts of parents and other working family members.
2. It Helps Students Develop Saving Habits
Saving money is one of the most useful financial habits students can develop.
Financial literacy teaches young learners that they do not need to spend every amount they receive. Keeping some money aside can help them achieve future goals and prepare for unexpected needs.
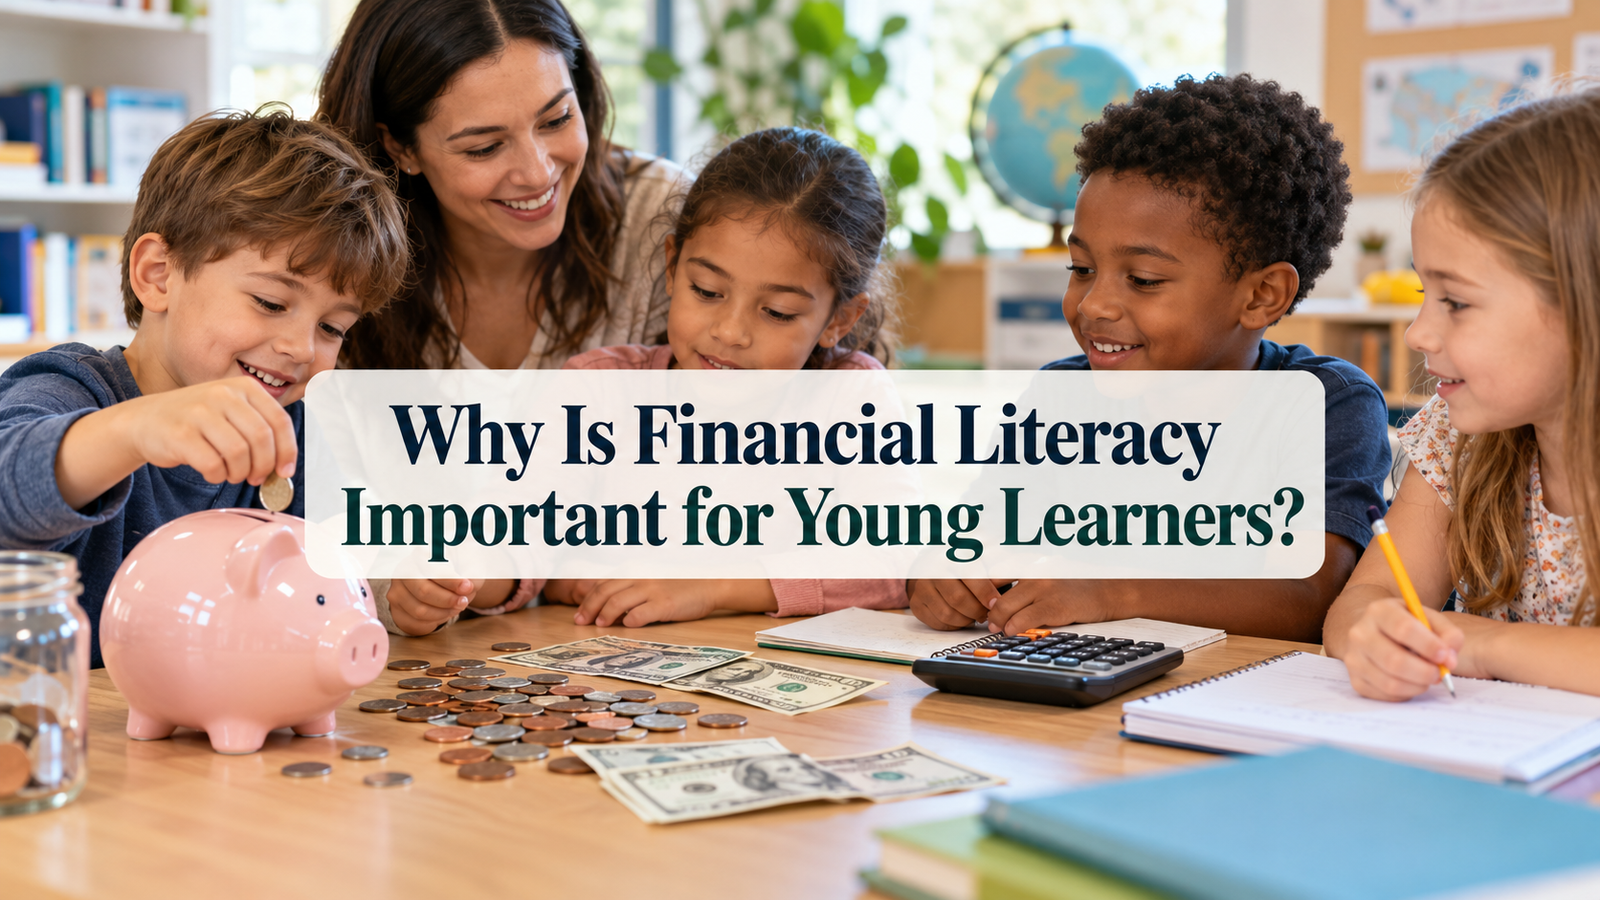
Children can begin with simple saving activities. They may use a money box, savings jar, or supervised savings account.
For example, a student who receives 500 rupees as pocket money may decide to save 100 rupees each week. Over several weeks, the student can observe how small savings gradually increase.
This experience teaches patience, consistency, and planning.
Teachers can introduce classroom activities where students create imaginary saving goals and calculate how much time is needed to reach them.
Learning to save at an early age can make it easier for students to develop responsible financial habits as adults.
3. Financial Education Explains Needs and Wants
Understanding the difference between needs and wants is a basic part of financial literacy.
Needs are essential items or services required for daily living. These include food, suitable clothing, shelter, education, and healthcare.
Wants are things that people would like to have but can often live without. Examples include expensive toys, fashionable accessories, and entertainment products.
Young learners may find it difficult to separate these categories because advertisements and social influences can make certain products appear necessary.
Financial education helps students examine their choices more carefully.
A teacher might ask students to classify different items as needs or wants. Students can then discuss why some purchases should receive greater priority than others.
This activity develops critical thinking and encourages thoughtful spending.
Students also learn that wants are not necessarily bad. The important lesson is to balance personal enjoyment with essential responsibilities.
4. It Encourages Responsible Spending Decisions
Financial literacy helps young learners understand how to make sensible purchasing decisions.
Without financial awareness, students may spend money quickly on items that provide only temporary satisfaction.
Learning responsible spending encourages them to compare prices, examine product quality, and think about whether a purchase is necessary.
For example, a student planning to buy a school bag may compare several options before choosing one. Instead of selecting the most expensive bag, the student may consider durability, comfort, size, and price.
This simple decision demonstrates how financial knowledge can influence everyday choices.
Teachers can organize classroom shopping activities using imaginary money and product price lists.
Students can practice selecting useful items while staying within a fixed budget.
These exercises help children understand that good spending decisions involve planning rather than purchasing everything they desire.
5. Financial Literacy Builds Budgeting Skills
Budgeting is the process of planning how available money will be used.
Although young learners may not have regular income, they can still understand basic budgeting principles through pocket money, gifts, or classroom examples.
A simple budget shows how money can be divided among different purposes.
For example, a student receiving 1,000 rupees may plan to spend 500 rupees on necessary items, save 300 rupees, and use 200 rupees for personal enjoyment.
The exact amounts may vary depending on individual circumstances.
The important lesson is that spending should be planned according to available resources.
Budgeting also teaches students to recognize financial limits. They learn that purchasing one item may reduce the money available for another.
These lessons are especially valuable as students become older and begin managing transportation costs, educational expenses, or personal purchases.
6. It Develops Better Decision Making Skills
Financial literacy supports the development of decision making skills.
Every financial choice involves considering different options and their possible consequences.
For example, a student may have enough money to purchase either a storybook or a game. Financial education encourages the student to think about personal priorities before making a decision.
The student may consider which item will provide greater value, how frequently it will be used, and whether saving for another purpose would be more beneficial.
This process develops reasoning and self control.
Students also become more comfortable evaluating information before taking action.
These skills extend beyond financial matters. Careful decision making can help learners manage their time, organize academic tasks, and make responsible personal choices.
Financial literacy therefore contributes to broader personal development.
7. It Prepares Students for Future Financial Responsibilities
Children eventually become adults who must manage their own financial affairs.
They may need to pay educational fees, maintain bank accounts, cover living expenses, and plan for long term goals.
Introducing financial education during childhood provides a foundation for understanding these responsibilities.
Older students can gradually learn about income, taxes, savings accounts, borrowing, and financial agreements.
They can also explore how interest works and why borrowing money requires careful consideration.
For example, students may learn that a loan must usually be repaid and that additional interest or fees can increase the total cost.
Understanding these basic principles can help young people recognize financial obligations before accepting them.
Early education does not guarantee that students will avoid every financial difficulty. However, it can provide useful knowledge for managing financial situations more confidently.
8. Financial Literacy Encourages Goal Setting
Setting financial goals gives young learners a practical reason to manage money carefully.
A financial goal may involve saving for books, educational materials, a bicycle, or another useful purchase.
Students learn that larger goals often require time and consistent effort.
Teachers can introduce activities where children write down a financial goal, estimate its cost, and calculate how much they need to save regularly.
For example, a student wanting to purchase a 2,000 rupee educational item can create a saving plan based on the money available each week.
Tracking progress helps students understand the relationship between planning and achievement.
Goal setting also encourages patience because learners begin to recognize that meaningful results may require delayed satisfaction.
This habit can support academic goals and other areas of personal growth.
9. It Helps Young Learners Understand Banking
Banking is an important part of modern financial life.
Young learners should gradually become familiar with basic banking concepts, including savings accounts, deposits, withdrawals, and digital payments.
For younger children, teachers can explain how banks help people store and manage money.
Older students can learn about bank statements, account balances, payment cards, and the importance of protecting financial information.
For example, students should understand that passwords, PINs, and one time verification codes must not be shared with other people.
They should also learn to recognize suspicious messages requesting personal or banking details.
Introducing these concepts helps students become more confident when using financial services in the future.
Financial education should also explain that different banking products have different terms, costs, and risks.
Understanding these differences encourages informed financial choices.
10. Financial Literacy Reduces the Risk of Poor Money Habits
Many financial difficulties arise when people develop spending habits without understanding their consequences.
Impulsive purchasing, unnecessary borrowing, and failing to plan expenses can create problems over time.
Financial literacy introduces preventive habits before students begin handling significant amounts of money.
Young learners can practice waiting before making purchases, comparing alternatives, and keeping simple spending records.
For example, a student may discover that buying snacks every day uses most of their weekly allowance.
Recording these expenses can help the student understand spending patterns and identify opportunities to save.
Financial education also teaches that mistakes can provide learning opportunities.
Rather than criticizing children for poor financial choices, parents and teachers can help them reflect on what happened and consider better alternatives.
This supportive approach encourages responsibility without creating fear or shame around money.
11. It Promotes Financial Independence and Confidence
Financial independence begins with the ability to understand and manage personal resources.
Young learners who receive suitable financial education may become more confident when making everyday money decisions.
They learn how to calculate costs, understand change, plan purchases, and monitor savings.
For example, a child who can compare prices and calculate the remaining balance after a purchase is practicing both financial and mathematical skills.
These experiences help students become less dependent on others for simple financial decisions.
However, financial independence should develop gradually and according to a child’s age and maturity.
Parents should continue providing guidance, particularly when financial choices involve online payments, contracts, or significant expenses.
The goal is not to make children responsible for adult financial problems. Instead, it is to provide age appropriate knowledge that supports future independence.
12. Financial Literacy Connects Classroom Learning With Real Life
One of the greatest benefits of financial literacy education is its connection with everyday experiences.
Students often study mathematics without immediately understanding how it applies outside school.
Financial activities provide practical examples of addition, subtraction, multiplication, division, percentages, and problem solving.
For example, calculating the total price of several products helps students practice addition. Working out a discount introduces percentages, while comparing saving plans develops numerical reasoning.
Teachers can also connect financial education with social studies by discussing how people earn income and how communities use economic resources.
Language lessons may involve reading advertisements or explaining financial decisions in writing.
These connections make learning more engaging and demonstrate how academic knowledge supports real responsibilities.
13. Parents Play an Important Role in Financial Literacy
Parents are often children’s first teachers when it comes to money.
Everyday family activities provide opportunities to introduce financial concepts naturally.
For example, parents can involve children in preparing shopping lists, comparing grocery prices, and planning small purchases.
They can explain why some items are purchased immediately while others must wait.
Providing an age appropriate allowance can also help children practice saving and spending decisions.
Parents should encourage questions about money without sharing financial pressures that children are not ready to handle.
Open conversations can help young learners develop a healthy understanding of financial responsibilities.
Children also learn through observation. When adults demonstrate thoughtful spending, planning, and responsible financial behavior, they provide useful examples for younger family members.
14. Schools Can Teach Financial Literacy Through Practical Activities
Schools can make financial education interesting by connecting lessons with realistic situations.
Students do not need advanced financial knowledge to begin learning.
Teachers can introduce simple activities involving money calculations, classroom shops, savings challenges, and budget planning.
For example, a classroom activity might give each group an imaginary budget of 5,000 rupees to organize a small educational event.
Students must decide how much to spend on materials, decorations, and other necessary items.
They can compare different options and explain their choices.
Such activities develop teamwork, communication, and financial reasoning.
Older students may benefit from discussions about online shopping, digital payments, financial scams, and responsible borrowing.
Schools should ensure that financial lessons remain inclusive and respectful of different family circumstances.
Practical financial education works best when students can participate without needing to disclose their household income or personal financial information.
15. Financial Literacy Supports Long Term Financial Wellbeing
The benefits of financial literacy can continue throughout a person’s life.
Students who understand saving, budgeting, and responsible spending have a stronger foundation for handling future financial decisions.
As they become adults, these skills may help them manage personal expenses, prepare for emergencies, and work toward important goals.
Financial knowledge can also help individuals recognize misleading financial offers and ask appropriate questions before making commitments.
It is important to understand that financial wellbeing depends on more than personal knowledge. Income, employment opportunities, living costs, and unexpected circumstances also influence financial stability.
Nevertheless, financial education gives young people useful tools for navigating these challenges.
By developing awareness early, students can approach financial responsibilities with greater understanding and confidence.
Frequently Asked Questions
At What Age Should Children Start Learning Financial Literacy?
Children can begin learning simple financial concepts during their early school years. Recognizing money, understanding prices, and distinguishing needs from wants are suitable starting points. More advanced subjects can be introduced as students become older.
Why Should Financial Literacy Be Taught in Schools?
Financial literacy should be taught in schools because it prepares students for practical responsibilities that are not always covered by traditional academic subjects. It helps them develop saving habits, budgeting skills, and responsible spending behavior.
How Can Parents Teach Children About Money?
Parents can teach children through everyday activities such as shopping, saving pocket money, comparing prices, and discussing spending choices. Simple explanations and practical experiences are often more effective than complicated financial lessons.
What Are the Most Important Financial Skills for Students?
Some of the most important financial skills include budgeting, saving, identifying needs and wants, comparing prices, setting financial goals, understanding basic banking, and protecting personal financial information.
Can Financial Literacy Improve Academic Learning?
Financial literacy can support academic learning by providing practical opportunities to apply mathematics, reading, reasoning, and problem solving skills. Financial activities can also encourage planning and responsible decision making.
Conclusion
Financial literacy is important for young learners because it provides essential knowledge for managing money and making responsible financial decisions. Understanding saving, budgeting, spending, and financial planning helps students develop habits that can benefit them throughout their lives.
Teaching financial concepts during childhood also encourages patience, confidence, critical thinking, and personal responsibility. Students begin to understand that money should be managed thoughtfully and that financial choices often have future consequences.
Parents and schools can work together to make financial education a natural part of everyday learning. Simple activities, practical examples, and supportive discussions can help children understand important concepts without making the subject unnecessarily complicated.
Financial literacy is not simply about teaching children how to handle money. It is about preparing them to make informed choices, understand their responsibilities, and approach future financial challenges with greater confidence.